Markets / Chicago CBD
The Chicago CBD is the largest office market in the Midwest, about 193 million SF across seven submarkets: the West Loop, Central Loop, East Loop, South Loop, River North, North Michigan Avenue, and Fulton Market. As of October 2026, about 22% of downtown office space sat vacant, down from about 23% a year ago, and downtown absorbed about 700,000 SF over the past year, led by River North, the West Loop, and Fulton Market. In the transactions we track and negotiate, Class A space leases for about $42 to $66 per SF gross depending on the submarket and Class B for about $26 to $40, with about 1 month of free rent per year of term and improvement allowances of $6 to $8 per SF per year of term ($60 to $80 on a 10-year lease), except in spec suites. Tenant Advisors represents only tenants.
Downtown is really seven markets. Vacancy runs from about 15% in Fulton Market to about 32% in the South Loop, and the submarkets are moving in different directions, so where you look decides how much leverage you have.
| October 2026 | Chicago CBD, all seven submarkets |
|---|---|
| Office inventory | About 193 million SF |
| Overall vacancy | About 22%, down from about 23% a year ago |
| Class A vacancy | About 23% |
| Class B vacancy | About 21% |
| Net absorption, last 12 months | About +700,000 SF |
| New construction underway | One 28,700 SF building on East Ohio Street (North Michigan Avenue submarket); no towers |
| Sublease space available | About 4.4 million SF |
| Submarket | Inventory | Vacancy | 12-month absorption | Class A, gross | Class B, gross |
|---|---|---|---|---|---|
| West Loop | About 62 million SF | 21%, down from 22% | About +370,000 SF | $48 to $56 | $34 to $40 |
| Central Loop | About 47 million SF | 22%, down from 24% | About +38,000 SF | $42 to $50 | $34 to $40 |
| East Loop | About 31 million SF | 27%, roughly flat | About -213,000 SF | $46 to $54 | $32 to $38 |
| River North | About 21 million SF | 22%, down from 25% | About +613,000 SF | $48 to $56 | $32 to $38 |
| North Michigan Avenue | About 17 million SF | 16%, up from 15% | About -520,000 SF | $42 to $50 | $34 to $40 |
| Fulton Market | About 13 million SF | 15%, down from 16% | About +349,000 SF | $58 to $66 | $32 to $38 |
| South Loop | About 3 million SF | 32%, down from 34% | About +66,000 SF | $34 to $40 | $26 to $32 |
| Lease terms we are negotiating downtown | Class A | Class B |
|---|---|---|
| Rent, gross per SF | About $42 to $66, depending on submarket | About $26 to $40, depending on submarket |
| Free rent | About 1 month per year of term | About 1 month per year of term |
| Improvement allowance | $6 to $8 per SF per year of term ($60 to $80 on a 10-year lease); none on spec suites | $6 to $8 per SF per year of term ($60 to $80 on a 10-year lease); none on spec suites |
| Free rent on a 10-year lease | Typically about 10 months | Typically about 10 months |
Rents and concessions reflect the downtown transactions Tenant Advisors tracks and negotiates as of October 2026. Results vary by building, size, term, and credit. Nothing taller than four stories is under construction downtown, and older buildings along LaSalle Street and elsewhere in the Loop are being converted to other uses, so the supply of office space is slowly shrinking.
Downtown is filling back up, but slowly, and the empty space is concentrated in older Loop buildings.
Downtown absorbed about 700,000 SF over the past year, which moved vacancy only from about 23% to about 22% on a base of about 193 million SF.
The South Loop is about 32% vacant and the East Loop about 27%, while Fulton Market is about 15%. North Michigan Avenue gave back about 520,000 SF of occupied space over the past year.
About 4.4 million SF of sublease space is on the market downtown, about 1.7 million SF of it in the West Loop.
The only office building under construction is a 28,700 SF building on East Ohio Street, and older Loop buildings are being converted to other uses, so the office inventory is slowly shrinking.
East Loop vacancy is about 27% and still edging up, and Central Loop Class A is about 29% vacant. Large towers such as Aon Center, One East Wacker, 77 West Wacker, and 70 W. Madison are carrying big blocks and competing hardest on rent and allowances.
River North absorbed about 613,000 SF over the past year and Fulton Market about 349,000 SF. Trophy towers such as 151 North Franklin, Salesforce Tower Chicago, and 333 N. Green are close to full, so tenants who want new trophy space should start early.
Many Loop office towers have sold over the past year for under $100 per SF, a fraction of their prior values. An owner who bought at that basis can offer lower rent and larger allowances and still make money, so find out who owns the building and what they paid.
About 4.4 million SF of sublease space is available downtown, much of it built out and furnished, including full floors in newer Fulton Market and West Loop buildings. And a renewal should be priced against all of it, not just your landlord’s asking rate.
The tenants most active in the Chicago CBD right now are:
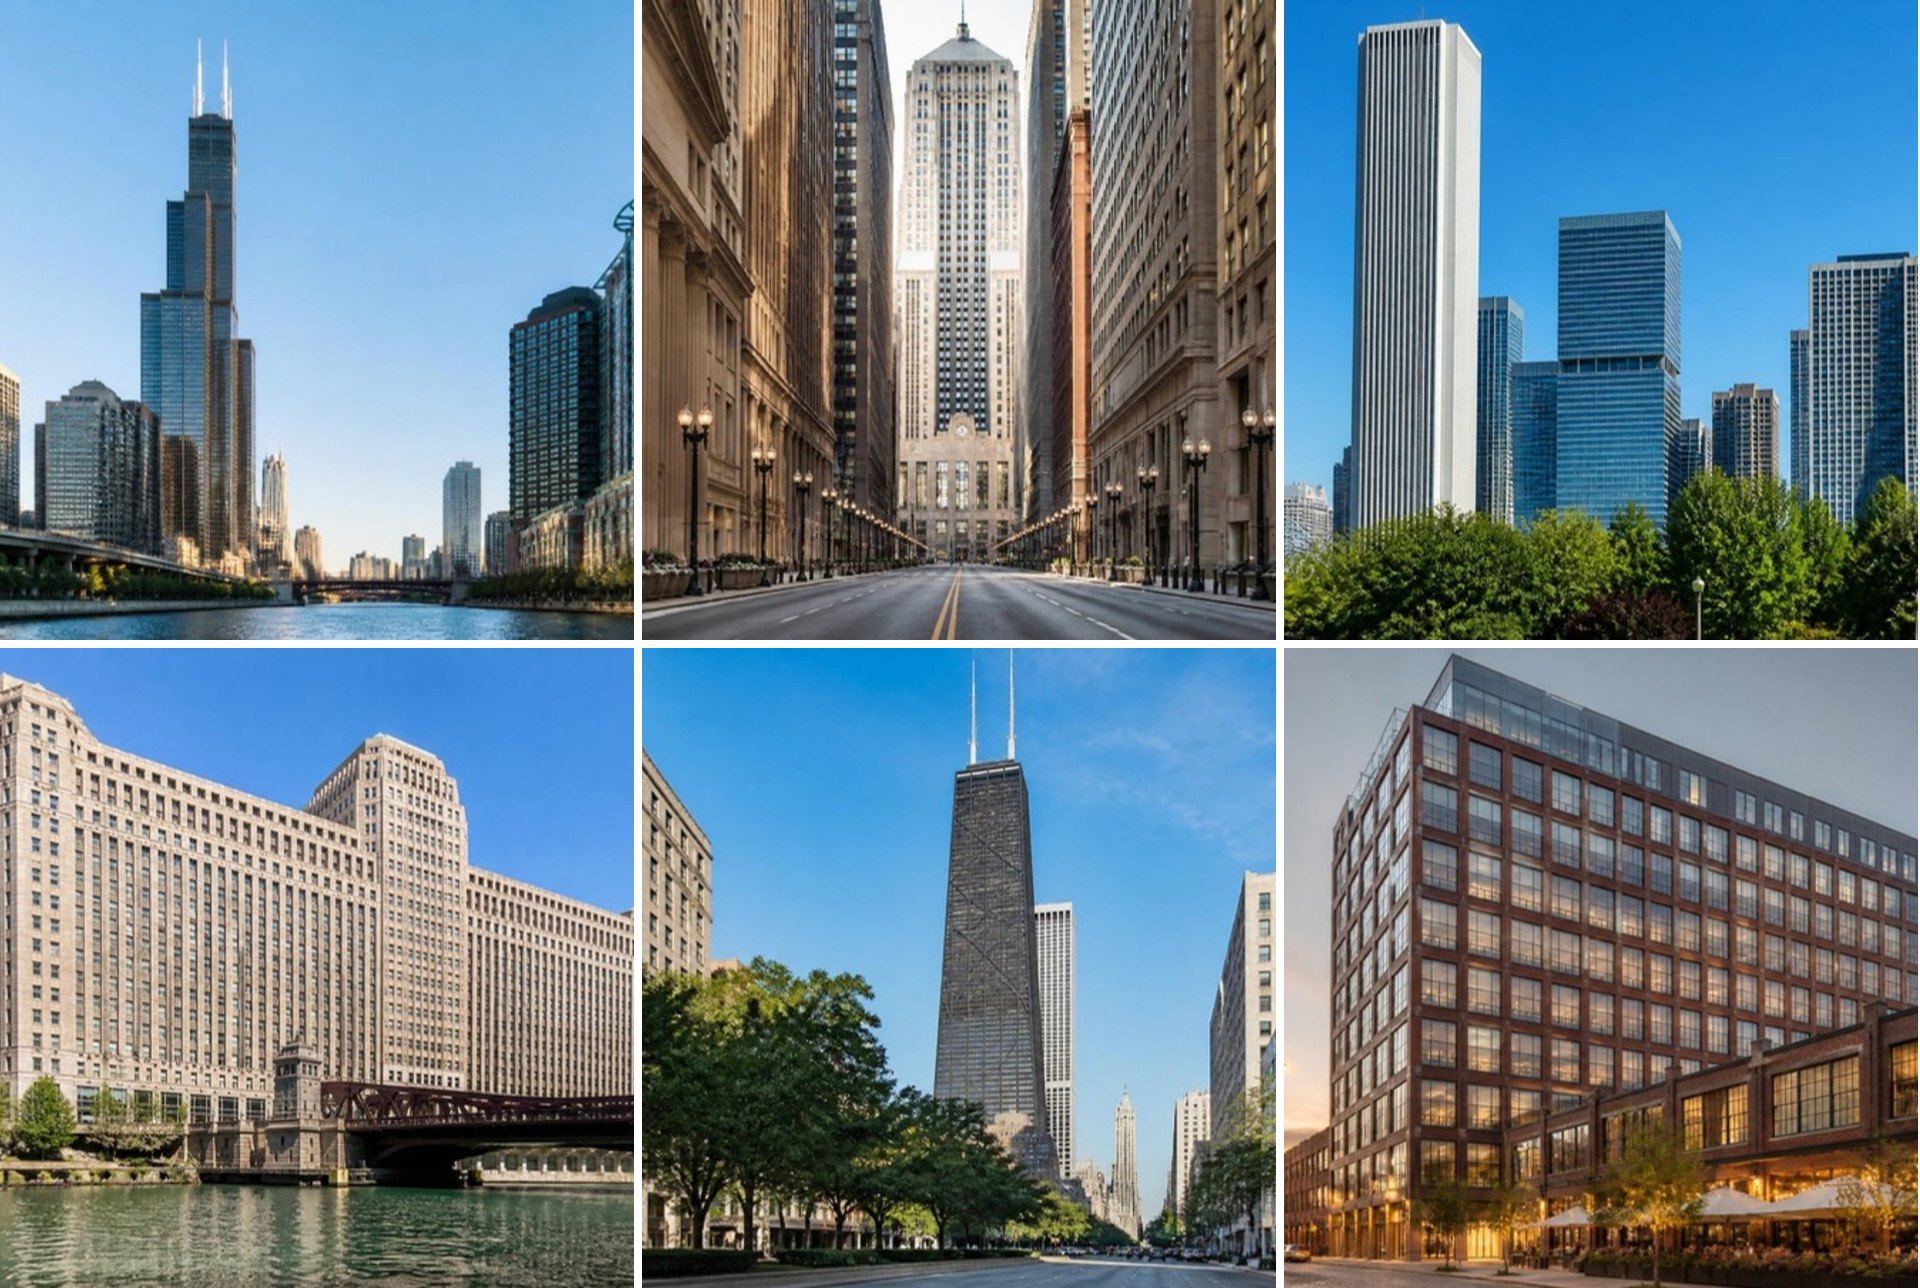
Three properties that shape pricing downtown. Figures are October 2026 and rounded.
The largest office building in Chicago, about 4 million SF and about 12% vacant. It added about 185,000 SF of occupied space over the past year, more than any other West Loop building.
About 960,000 SF on the river. It gained about 317,000 SF of occupied space in the past year, the most in the Central Loop, and is still about 38% vacant, so large blocks remain.
About 3.7 million SF on the north bank of the river and about 22% vacant. It added about 134,000 SF of occupied space over the past year, the most of any River North building.
We don’t represent any of these landlords. Ask us which buildings fit your size, budget, and term, and what they are actually conceding.
Many of the brokers working downtown Chicago also lease buildings for landlords here. Tenant Advisors has represented only tenants since 2004 and doesn’t own or manage office buildings, so every downtown building is on the table and every landlord is someone we negotiate against.
As of October 2026, about 22% of the roughly 193 million SF of office space in the Chicago CBD was vacant, down from about 23% a year earlier. Class A vacancy was about 23% and Class B about 21%. Figures are rounded Tenant Advisors Market Data.
Fulton Market has the lowest, about 15%, followed by North Michigan Avenue at about 16%. The South Loop has the highest, about 32%, and the East Loop is about 27%.
In the transactions we track and negotiate as of October 2026, Class A office space downtown leases for about $42 to $66 per SF gross, from about $42 to $50 in the Central Loop and on North Michigan Avenue to about $58 to $66 in Fulton Market. Class B leases for about $26 to $40.
Typically about 1 month of free rent per year of lease term, or about 10 months on a 10-year lease, plus improvement allowances of $6 to $8 per SF per year of term, or $60 to $80 on a 10-year lease. Spec suites are delivered built and carry no allowance. Tenants who create competition between buildings get the upper end.
Seven: the West Loop, Central Loop, East Loop, South Loop, River North, North Michigan Avenue (the Magnificent Mile and Streeterville), and Fulton Market and the Near West Side.
Overall, slowly. The CBD absorbed about 700,000 SF over the past year. River North (about +613,000 SF), the West Loop (about +370,000 SF), and Fulton Market (about +349,000 SF) gained the most, while North Michigan Avenue (about -520,000 SF) and the East Loop (about -213,000 SF) lost occupied space.
About 4.4 million SF, much of it built out and often furnished. The West Loop has the most, about 1.7 million SF, and Fulton Market has the highest share of its inventory, about 5%.
Almost none. The only office building under construction is a 28,700 SF building on East Ohio Street. About 2.6 million SF is proposed in Fulton Market and a 665,000 SF tower is proposed at 590 W. Madison Street in the West Loop, but none would deliver before 2028.